
The cheapest premium doesn't necessarily buy the best final expense insurance. Similar monthly payments can purchase different death benefits, underwriting requirements, cash-value provisions, and early-claim restrictions. A policy that looks affordable in an advertisement may leave your family with less usable protection than you expected.
Compare an actual policy illustration, not just a headline rate. Your comparison should reflect age, sex, state, health, coverage amount, and underwriting class where applicable. Ask for the total premium, guaranteed death benefit, and benefit payable during any initial limited-benefit period. Don't assume that no medical exam means no health screening, or that permanent coverage means every death immediately qualifies for the full benefit.
These options represent distinct buying paths: an educational starting point, direct guaranteed-issue coverage, digitally underwritten protection, local-agent service, and membership-based eligibility. They aren't interchangeable, and their order isn't a universal carrier ranking.
Start with the obligation: Choose the amount your family needs before choosing the application process you prefer.
For contractors, early retirees, and households without dependable workplace benefits, the decisive question is whether the policy addresses the actual financial gap without creating a premium commitment that's difficult to maintain.
1. Your Guide to Final Expense Insurance
Best starting point for buyers who haven't separated funeral costs from broader family protection. My Policy Quote's guide to final expense insurance describes smaller whole-life coverage intended to help with funeral bills, unpaid medical expenses, and other end-of-life obligations. It's an educational resource, not an insurance contract or a substitute for a personalized quote.
That distinction matters because a final-expense budget can be substantial without representing the household's entire insurance need. The NFDA's 2023 General Price List Study reported a national median of $8,300 for a funeral with viewing and burial, excluding a vault, and $6,280 for a funeral with viewing and cremation. Those funeral-home figures don't necessarily include every cemetery, transportation, memorial, or administrative expense.
Decide What You're Protecting
The guide is most useful before you request coverage. Separate the money needed for final arrangements from the money a surviving spouse would need for housing, groceries, caregiving, and other continuing obligations. A smaller policy may address the former without adequately covering the latter.
- Strength: The guide connects insurance to identifiable expenses rather than treating a large death benefit as automatically necessary.
- Limitation: It doesn't establish which carrier will accept you, what you'll pay, or which benefit restrictions your contract will contain.
- Best use: Prepare a written coverage target and bring it to a licensed agent for product-specific comparisons.
If you're self-employed, don't count hypothetical future workplace coverage as an existing resource. Likewise, parents considering coverage for an adult child should distinguish end-of-life costs from the financial support that child provides to dependents.
Insurance planning also belongs alongside beneficiary and estate planning. If you're working to secure your family's legacy, coordinate those decisions rather than assuming an insurance purchase resolves every inheritance or administrative concern.
The analytical advantage is better problem definition. You can reject an unsuitable policy sooner when you know whether you need funeral liquidity, broader income protection, or both.
2. Mutual of Omaha, Whole Life / Living Promise
Mutual of Omaha deserves consideration when you want to compare different underwriting routes within the same insurer, rather than immediately defaulting to guaranteed acceptance. Its direct whole-life offering and agent-assisted Living Promise coverage should be treated as separate quote requests.
The Mutual of Omaha whole-life information page describes direct guaranteed-acceptance coverage of $2,000–$25,000, generally for eligible applicants ages 45–85 in most states, with a two-year limited natural-cause benefit period. That direct option requires no medical exam or health questions, while Living Promise offers agent-assisted level- and graded-benefit choices.
Compare the Contract, Not the Company Name
A level benefit generally means the stated death benefit applies without a graded reduction, subject to the contract. A graded benefit limits what beneficiaries receive during an initial period. Ask the agent which version you qualify for and request its specific early-death payment provisions in writing.
- Direct guaranteed acceptance: A practical route for applicants prioritizing no-health-question eligibility.
- Agent-assisted Living Promise: Worth exploring if you're willing to answer underwriting questions and compare benefit structures.
- Main trade-off: Easier acceptance may come with less favorable pricing or early natural-cause protection than a health-underwritten alternative.
The online quote flow and final-expense calculator can support initial planning, but they shouldn't replace a state-specific illustration. Confirm that the quoted product, premium, and benefit schedule belong to the same policy version.
For a buyer managing a chronic condition, the useful question isn't whether acceptance is guaranteed. It's whether an agent-assisted option offers suitable terms before you commit to the no-health-question route. Don't assume that a health condition automatically eliminates every underwritten option.
3. AARP Life Insurance Program from New York Life, Guaranteed Acceptance
Membership eligibility comes before price comparison. The AARP Guaranteed Acceptance Life Insurance program from New York Life is available to eligible members and spouses or partners, requires no medical exam or health questions, and generally limits natural-cause death benefits during the first two years. Age eligibility and application methods depend on state rules.
This route may suit an eligible older adult who wants coverage without health screening. Required premiums keep permanent coverage in force, and the premium is fixed based on age at application. However, membership access doesn't establish that the policy offers the strongest value for your particular health profile.
Acceptance answers whether you can obtain the policy. The benefit schedule answers how much protection your family actually receives.
For someone comparing coverage for a spouse, eligibility must be checked for that applicant, not inferred from the member's own eligibility. My Policy Quote's guide to life insurance for seniors provides a broader starting point for considering whether final-expense coverage fits the household's needs.
Treat Cash Value as a Separate Comparison
This product builds cash value, with policy loans potentially available. Don't equate cash value with the death benefit or treat it as an immediately accessible replacement for emergency savings.
Request the guaranteed cash-value schedule and any loan provisions before assigning value to that feature. Ask the insurer to explain how borrowing, unpaid interest, or surrender would affect the policy.
The strongest buyer match is an eligible applicant who prioritizes straightforward acceptance and understands the initial restriction. The weaker match is someone who could obtain suitable health-underwritten coverage but chooses this policy solely because the membership connection feels familiar.
4. Transamerica, FE Express Solution
Digital convenience isn't guaranteed acceptance. Transamerica's FE Express Solution is a whole-life option with a simplified digital application, making it a different buying path from the no-health-question products elsewhere on this list.
The Transamerica final-expense product page describes potential coverage of $25,000–$100,000, depending on age, and eligibility decisions in as little as 10 minutes, alongside funeral-planning resources. Those are product parameters, not a promise that every applicant receives approval or qualifies for the maximum benefit.
This route may interest applicants who are comfortable with a digital process and need more protection than a modest guaranteed-issue policy offers. But convenience should be evaluated alongside health questions, authorized data checks, the actual benefit schedule, and premium affordability.
- Underwriting: Ask what information the application requires and whether further review could be necessary.
- Benefit: Confirm the guaranteed amount you're offered, rather than relying on the advertised maximum.
- Availability: Verify the current product in your state, particularly because the former Final Expense Solutions Portfolio has been withdrawn in most states.
Choose Speed Without Confusing the Routes
Simplified underwriting and guaranteed issue solve different problems. My Policy Quote's explanation of guaranteed-issue life insurance can help you distinguish acceptance without health screening from an application that still evaluates eligibility.
The distinction has practical importance: LIMRA research on simplified underwriting found that 53% of consumers surveyed in late 2020 said awareness of simplified underwriting increased their likelihood of buying life insurance. That measures consumer interest, not approval rates or policy quality.
For a qualified applicant, FE Express Solution is worth comparing on protection and price. A quick decision is useful only if the resulting contract meets the need.
5. Gerber Life, Guaranteed Life Insurance
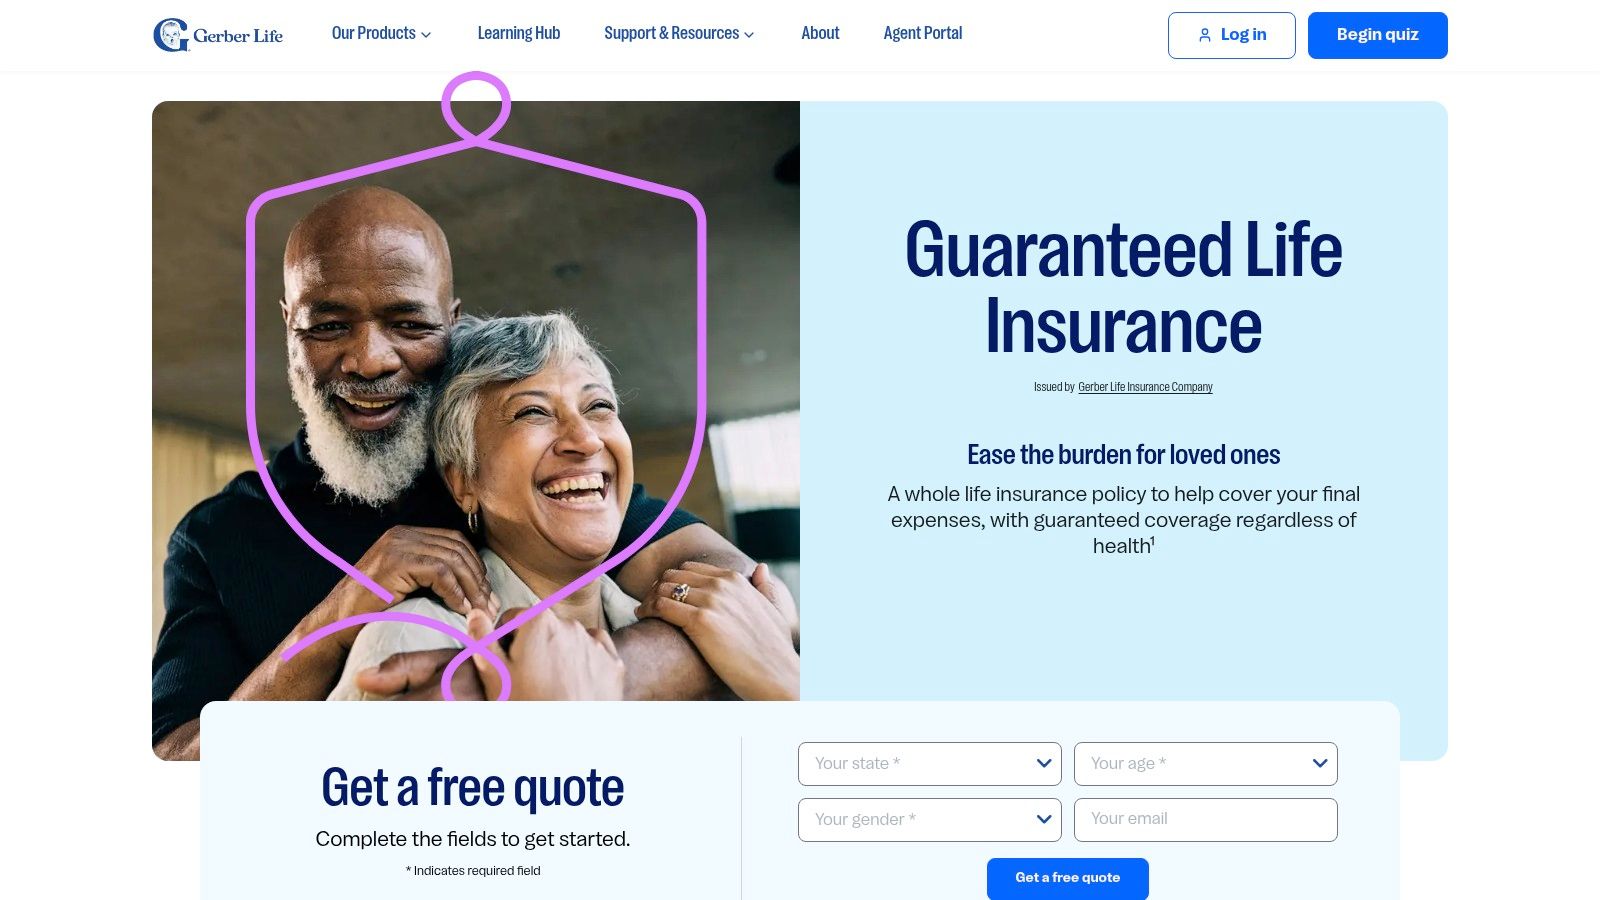
Gerber Life is a candidate for buyers who have difficulty qualifying for medically underwritten coverage and want a modest, defined death benefit. Its appeal is straightforward eligibility, not a promise to solve every surviving-family expense.
The Gerber Life Guaranteed Life Insurance page describes coverage generally available to eligible applicants ages 50–80, with benefits generally ranging from $5,000 to $25,000, subject to state exceptions; the product is not available in Montana. It requires no medical exam or health questions and is designed to remain in force for life while premiums are paid.
Match the Benefit to the Remaining Gap
A smaller policy can make sense when existing savings or other insurance already cover broader household needs. It's less compelling when the proposed benefit must also replace a wage earner's income or protect a substantial housing obligation.
The NAIC Life Insurance Buyer's Guide identifies funeral costs, medical or nursing-care expenses, debt repayment, child care, and lost income as possible uses of life-insurance proceeds. Final expense describes a planning purpose, not proof that beneficiaries must spend the proceeds only on a funeral.
Use My Policy Quote's burial insurance versus life insurance comparison to clarify that distinction before selecting a benefit amount.
- Good fit: An eligible applicant seeking acceptance without health screening for a limited final-expense obligation.
- Potential mismatch: A household expecting the same modest benefit to cover funeral costs and sustained income loss.
- Contract question: Confirm the initial limited-benefit provisions, including the payment for an early natural-cause death.
Gerber's simple application doesn't remove the need for detailed comparison. Ask for the same target benefit from competing insurers so that you're comparing equivalent protection, not differently sized policies.
6. State Farm, Guaranteed Issue Whole Life
Some buyers need a conversation more than a self-service application. State Farm's agent-based route may suit someone who wants help understanding eligibility, beneficiary choices, and benefit restrictions before committing.
The State Farm final-expense insurance page describes guaranteed-issue whole-life coverage of $10,000–$15,000, without health questions or a medical exam, with a limited natural-cause benefit during the first two years. Premiums don't increase, and coverage is permanent while required premiums are paid.
The narrow benefit range is both a convenience and a constraint. It may simplify the decision for someone whose uncovered final costs fit the available amounts, but it may not match a smaller gap or a larger family obligation.
Bring the comparison to the appointment: Ask the agent to explain the early-death benefit using the actual policy form, not only the sales summary.
Agent access can be valuable for buyers who prefer discussing coverage face to face. It doesn't, by itself, establish that the policy is cheaper or more protective than another guaranteed-issue option.
Make the Appointment Product-Specific
Ask the agent to identify the applicable state policy, total premium, guaranteed benefit, and any cash-value or surrender provisions. If a family member helps with the purchase, include that person in the explanation while keeping the insured applicant's eligibility and coverage needs central.
Fixed premiums support predictable budgeting, but affordability still depends on the household. For a contractor with uneven income or an early retiree drawing on savings, review whether the payment commitment remains manageable during lean periods.
State Farm is most relevant when its available benefit fits the need and the buyer values agent guidance. Don't select it merely to avoid an online application if a different policy offers materially better terms.
7. Colonial Penn, Guaranteed Acceptance Life Insurance
A unit price isn't a coverage amount. Colonial Penn requires particular attention because its advertised pricing format can make comparisons misleading unless you translate the quote into an actual death benefit and total payment.
The Colonial Penn Guaranteed Acceptance Life Insurance page advertises $9.95 per unit, permits selection of up to 25 units, and generally serves eligible applicants ages 50–85, with a two-year limited-benefit period. The benefit per unit varies by age, gender, and state, so the advertised price doesn't identify a fixed amount of protection.
Guaranteed acceptance without health questions or a medical exam may make the product relevant to applicants who can't obtain suitable underwritten coverage. Permanent whole-life protection can address a defined final-expense need while required premiums are paid.
Translate Units Into Usable Protection
Before comparing Colonial Penn with Gerber, Mutual of Omaha, or another insurer, request a quote showing:
- Total death benefit: The actual guaranteed amount represented by your selected units.
- Total premium: The complete recurring payment, not the price of an individual unit.
- Initial benefit: The amount payable under the limited-benefit rules.
- Policy values: Any guaranteed cash-value schedule and surrender terms.
Don't compare a competitor's complete monthly premium with Colonial Penn's individual-unit price. Match the benefit amounts as closely as possible, then review the respective early-claim restrictions.
The useful buyer match is an eligible applicant who needs guaranteed acceptance and receives a competitive actual quote. The poor match is anyone choosing primarily because the advertised unit price looks low.
The analytical test is simple: Once you remove the unit format, does the policy still offer suitable protection at a sustainable total premium? If that answer isn't clear, the quote isn't ready for a purchase decision.
Best Final Expense Insurance: 7-Option Comparison
| Option | 🔄 Complexity / Access | 📊 Coverage / Expected Outcome | ⚡ Resource Requirements | ⭐ Key Advantage | 💡 Best Fit / Key Caveat |
|---|---|---|---|---|---|
| Your Guide to Final Expense Insurance | Informational; no application process | Explains how smaller whole-life coverage may help pay funeral and other final expenses | Time to read and compare policy terms and costs | ⭐ Clarifies how final expense coverage differs from broader life insurance | 💡 Useful starting point; not a policy or substitute for income protection |
| Mutual of Omaha, Whole Life / Living Promise | Direct guaranteed-acceptance option or agent-assisted application | Direct option offers $2,000–$25,000 in most states; permanent coverage | Quote flow or agent; direct option has no health questions or medical exam | ⭐ Offers both direct and agent-assisted paths | 💡 Compare costs and the direct option's two-year limited natural-cause benefit period |
| AARP Life Insurance Program from New York Life, Guaranteed Acceptance | Online or mail application, depending on state | Permanent coverage while premiums are paid; benefit amount varies | AARP membership; no health questions or medical exam | ⭐ Guaranteed acceptance for eligible members and spouses or partners | 💡 Check state age limits and the initial limited-benefit period |
| Transamerica, FE Express Solution | Digital application with simplified underwriting | $25,000–$100,000, depending on age; lifetime coverage while premiums are paid | Online application; eligibility depends on underwriting | ⚡ Eligibility decisions may be available in as little as 10 minutes | 💡 Consider for higher coverage needs; confirm current product and state availability |
| Gerber Life, Guaranteed Life Insurance | Straightforward guaranteed-acceptance application | Generally $5,000–$25,000; lifelong coverage while premiums are paid | No health questions or medical exam; age and state restrictions apply | ⭐ May be accessible to applicants who have difficulty qualifying elsewhere | 💡 Check limited-benefit terms and whether the coverage ceiling meets your needs |
| State Farm, Guaranteed Issue Whole Life | Apply through a local agent | $10,000–$15,000; level premiums and permanent coverage | Agent contact; no health questions or medical exam | ⭐ Local-agent support and fixed premiums | 💡 Modest coverage range; first two years have a limited natural-cause benefit |
| Colonial Penn, Guaranteed Acceptance Life Insurance | Request a quote; coverage is selected in units | Permanent coverage; benefit per unit varies by age, gender, and state | No health questions or medical exam; generally ages 50–85 | ⭐ Guaranteed acceptance for eligible applicants | 💡 Compare actual benefit and total premium; a two-year limited-benefit period applies |
Build the Shortlist Before You Buy
Start with local funeral, burial, or cremation estimates, then add relevant medical bills, debts, and other immediate obligations. Separate those costs from the support a surviving spouse or dependent would need afterward. Subtract savings specifically earmarked for these expenses and existing coverage you've confirmed will remain available.
That broader assessment matters for families relying on a primary earner. LIMRA's 2025 life-insurance facts report that 47% of surveyed households would have difficulty paying living expenses within six months after the primary wage earner's death. A funeral-sized policy may therefore be appropriate as one part of protection, but insufficient as the entire plan.
Compare Equivalent Offers
Obtain competing actual quotes for the same coverage target wherever possible. Use My Policy Quote to organize initial research and explore available options through licensed agents, rather than relying on advertising alone.
- Premium commitment: Compare the total recurring payment and premium-payment terms, not just an advertised starting price.
- Guaranteed protection: Identify the face amount and the benefit payable during any graded or limited-benefit period.
- Eligibility and availability: Confirm state rules, applicant requirements, and which product version you're being offered.
- Policy access and exit: Examine guaranteed cash values, surrender charges, loan provisions, and whether any conversion rights exist.
Also review contestability provisions and insurer complaint history before purchasing. Don't confuse a limited-benefit period with contestability: ask the agent to explain each separately and point to the relevant contract language.
The best final expense insurance is the policy that fits both the liability and the buyer. Qualified applicants should compare health-underwritten digital coverage before paying for guaranteed acceptance. Buyers who need easier acceptance should compare guaranteed-issue plans on actual benefits and restrictions, not just application simplicity.
Membership-based products belong on the shortlist only when eligibility is confirmed. Agent-assisted options deserve consideration when personalized explanation helps you make an informed choice. Across every route, the cheapest advertised premium may not provide the most useful coverage.
My Policy Quote offers final-expense insurance information and quote comparisons that can connect you with licensed insurance agents. Visit My Policy Quote to organize your coverage target and compare available options by actual premium, guaranteed benefit, underwriting route, and policy limitations.